Your Trusted Ottawa Mortgage Broker
Personalized mortgage solutions for homebuyers, homeowners, and real estate investors across Ottawa.
Mortgage Pre-Approval
Know your budget and shop for your new home with confidence
Mortgage Renewals
Compare your options before accepting your lender’s renewal offer
Mortgage Refinance
Access your home equity, consolidate debt, or improve your cash flow
Financing Solutions
Explore mortgage options tailored to your income and financial goals
Ready to Apply?
Complete my secure online application, and I’ll personally follow up with the next steps
MEET VANESSA WILSON
Mortgage advice built around your goals
Clear advice. Better options. Confident decisions.
Finding the right mortgage is about more than securing a competitive rate—it’s about choosing a strategy that supports your goals.
I’m Vanessa Wilson, an Ottawa Mortgage Agent Level 2. I help homebuyers and homeowners understand their options, compare lenders and move confidently through buying, renewing, refinancing or more complex financing.
✓ Access to banks, credit unions, monoline and alternative lenders
✓ Personalized solutions for straightforward and complex needs
✓ Hands-on support from application through closing
PERSONAL MORTGAGE GUIDANCE
Prefer to speak with me directly?
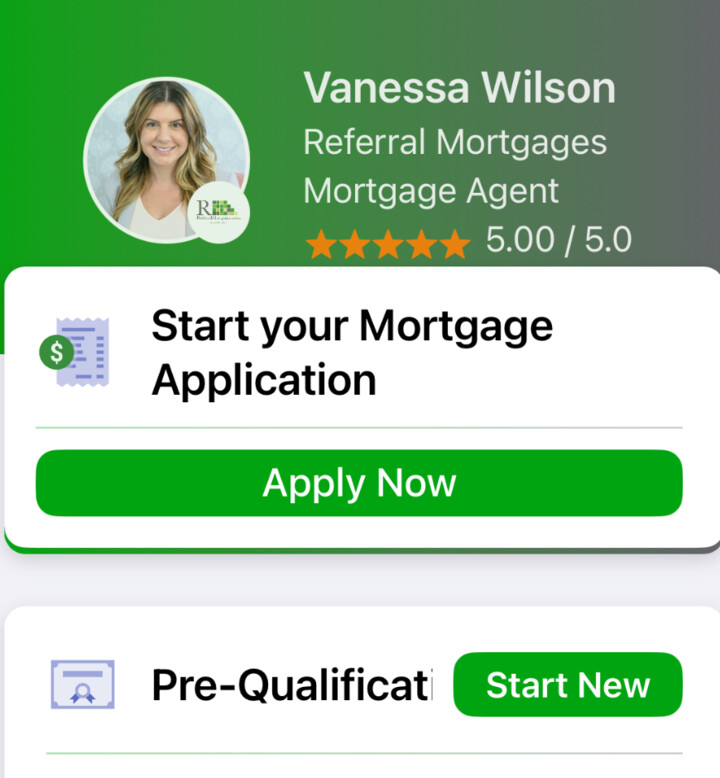
FREE CANADIAN MORTGAGE APP
See how much home you may be able to afford
Download my free Canadian Mortgage App, select 'Pre-Qualification' and tap 'Start New' to receive a quick estimate without affecting your credit score.
Pre-qualification provides an estimate only and is not a mortgage approval.
Bank of Canada Rate Increase October 2026 | Ottawa Mortgages
Bank of Canada Raises Interest Rates to 2.50%: What This Means for Canadian Homeowners
October 30, 2026 | By Vanessa Wilson, Mortgage Agent Level 2 — Referral Mortgages
On October 28, 2026, the Bank of Canada increased its benchmark interest rate by 0.25%, bringing it to 2.50%. This marks the first interest rate increase since July 2023 and could signal a shift in the direction of Canadian mortgage rates.
The decision comes as inflation remains persistent, driven largely by rising energy prices and increasing costs for Canadian businesses and households.
The Bank of Canada has also indicated that additional interest rate increases may be necessary, although future decisions will depend on economic conditions.
For Canadian homeowners, homebuyers, and those approaching a mortgage renewal, understanding how these changes affect your mortgage is more important than ever.
What Is Canada's New Prime Lending Rate?
Following the Bank of Canada's announcement, most major Canadian lenders increased their prime lending rate from 4.45% to 4.70%, effective October 29, 2026.
TD Bank's separate mortgage prime rate, used for certain variable-rate mortgages, has increased to 4.85%.
The prime lending rate is important because it directly influences the interest rates charged on variable-rate mortgages and home equity lines of credit (HELOCs).
However, the impact on your mortgage depends on the type of mortgage you have.
How Does the Rate Increase Affect Your Mortgage?
1. Fixed-Rate Mortgages: No Immediate Impact
If you currently have a fixed-rate mortgage, there's good news.
Your existing interest rate and regular mortgage payments will remain unchanged for the remainder of your term.
However, if your mortgage is coming up for renewal, it's important to recognize that fixed mortgage rates have also been increasing.
Unlike variable rates, fixed mortgage rates are influenced primarily by government bond yields and broader financial market conditions rather than directly by the Bank of Canada's overnight rate.
This means fixed rates can increase even when the Bank of Canada holds its benchmark rate steady.
2. Adjustable-Rate Mortgages: Your Payments Will Increase
If you have an adjustable-rate mortgage, your interest rate will increase by 0.25%, assuming your lender passes along the full increase.
Because adjustable-rate mortgage payments fluctuate with changes to the prime lending rate, you can expect your next mortgage payment to increase according to your lender's adjustment schedule.
The amount of your payment increase will depend on your outstanding mortgage balance, remaining amortization, and lender.
3. Static Variable-Rate Mortgages: Your Payment May Stay the Same
If you have a static-payment variable-rate mortgage, your regular payment generally remains unchanged when interest rates increase.
However, there is an important distinction.
More of each payment will now go toward interest, and less will go toward reducing your mortgage principal.
Over time, this can slow down your mortgage repayment and potentially extend your amortization.
If rates increase significantly, some mortgages may also reach their trigger rate, potentially requiring a payment adjustment or other action under the lender's terms.
4. Home Equity Lines of Credit (HELOCs): Higher Interest Costs
For homeowners with a HELOC, the increase in prime means higher borrowing costs.
For example, on an outstanding HELOC balance of $100,000, a 0.25% interest rate increase translates to approximately $250 in additional interest annually, assuming the balance remains unchanged.
While that may not sound significant on its own, multiple rate increases can add up over time.
My Recommendation for Variable-Rate Mortgage Holders
I've been encouraging my clients with variable-rate mortgages to proactively increase their regular mortgage payments wherever their budgets allow.
Making additional payments can help:
Reduce your outstanding mortgage balance faster.
Offset some of the impact of rising interest rates.
Keep your amortization closer to its original schedule.
Reduce the total interest paid over the life of your mortgage.
Even a relatively small increase in your regular payment can make a meaningful difference over time.
Before making changes, it's important to understand your lender's prepayment privileges and how additional payments are applied.
Buying a Home or Renewing Your Mortgage in the Next 12 Months?
If you're planning to purchase a home or your mortgage is coming up for renewal within the next year, now is a good time to review your mortgage strategy.
With fixed mortgage rates already moving higher and the possibility of additional Bank of Canada increases, planning ahead can help you make more informed decisions.
Should You Lock In a Fixed Mortgage Rate?
If your preference is a fixed-rate mortgage, I recommend securing a rate hold as soon as you're eligible.
Many lenders offer rate holds of approximately 120 days, which can provide protection against further fixed-rate increases while you finalize your purchase or renewal.
If your mortgage renewal is more than four months away, it's still worth reviewing your options early so you're prepared when the appropriate rate-hold window opens.
Is a Variable-Rate Mortgage Still Worth Considering?
Variable-rate mortgages may still offer competitive interest rates compared with fixed-rate options.
However, with the possibility of further rate increases, borrowers need to consider more than just the starting interest rate.
Your monthly budget, tolerance for payment fluctuations, mortgage terms, and long-term financial goals should all factor into the decision.
There isn't one mortgage product that's right for everyone.
Will the Bank of Canada Raise Rates Again in 2026?
The Bank of Canada's next scheduled interest rate announcement is December 9, 2026.
Although further increases are possible, nothing is guaranteed.
The Bank will continue monitoring inflation, economic growth, energy prices, and other developments before making its next decision.
For homeowners and prospective buyers, this reinforces the importance of having a mortgage strategy that can adapt to changing market conditions.
Let's Review Your Mortgage Strategy
Whether you're preparing to purchase a home, approaching your mortgage renewal, considering a refinance, or simply want to make sure your current mortgage is still working for you, I'm here to help.
As an Ottawa mortgage agent with Referral Mortgages, I work with clients to compare mortgage options across multiple lenders and develop financing strategies based on their individual needs and goals.
Click here to book a call with me to discuss your mortgage options.
Vanessa Wilson
Mortgage Agent Level 2 | Referral Mortgages
Source: Bank of Canada — October 28, 2026 Interest Rate Announcement
Disclaimer: This article provides general information for educational purposes. Mortgage rates, terms, and eligibility vary by lender and individual circumstances.
MY LENDER NETWORK
More lenders. More options.
I compare solutions from banks, credit unions, monoline lenders and alternative lenders to find the right fit for you.
ABOUT VANESSA
Vanessa Wilson
Mortgage Agent Level 2
Licence #M21002877
Clear advice. Personalized mortgage strategies. Support you can count on.