Your Trusted Ottawa Mortgage Broker
Personalized mortgage solutions for homebuyers, homeowners, and real estate investors across Ottawa.
Mortgage Pre-Approval
Know your budget and shop for your new home with confidence
Mortgage Renewals
Compare your options before accepting your lender’s renewal offer
Mortgage Refinance
Access your home equity, consolidate debt, or improve your cash flow
Financing Solutions
Explore mortgage options tailored to your income and financial goals
Ready to Apply?
Complete my secure online application, and I’ll personally follow up with the next steps
MEET VANESSA WILSON
Mortgage advice built around your goals
Clear advice. Better options. Confident decisions.
Finding the right mortgage is about more than securing a competitive rate—it’s about choosing a strategy that supports your goals.
I’m Vanessa Wilson, an Ottawa Mortgage Agent Level 2. I help homebuyers and homeowners understand their options, compare lenders and move confidently through buying, renewing, refinancing or more complex financing.
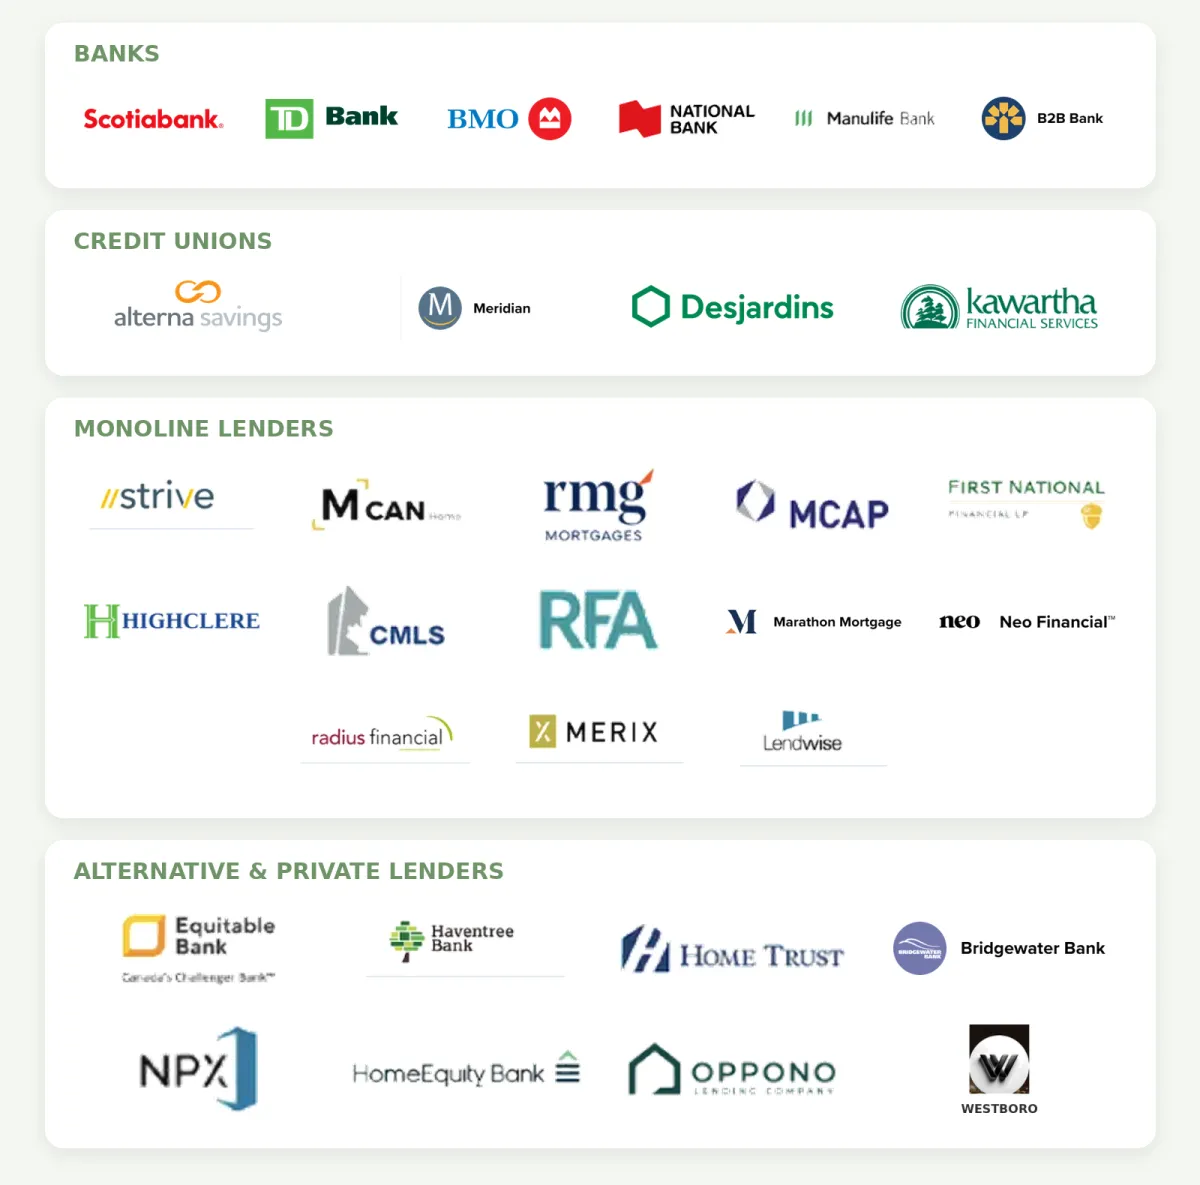
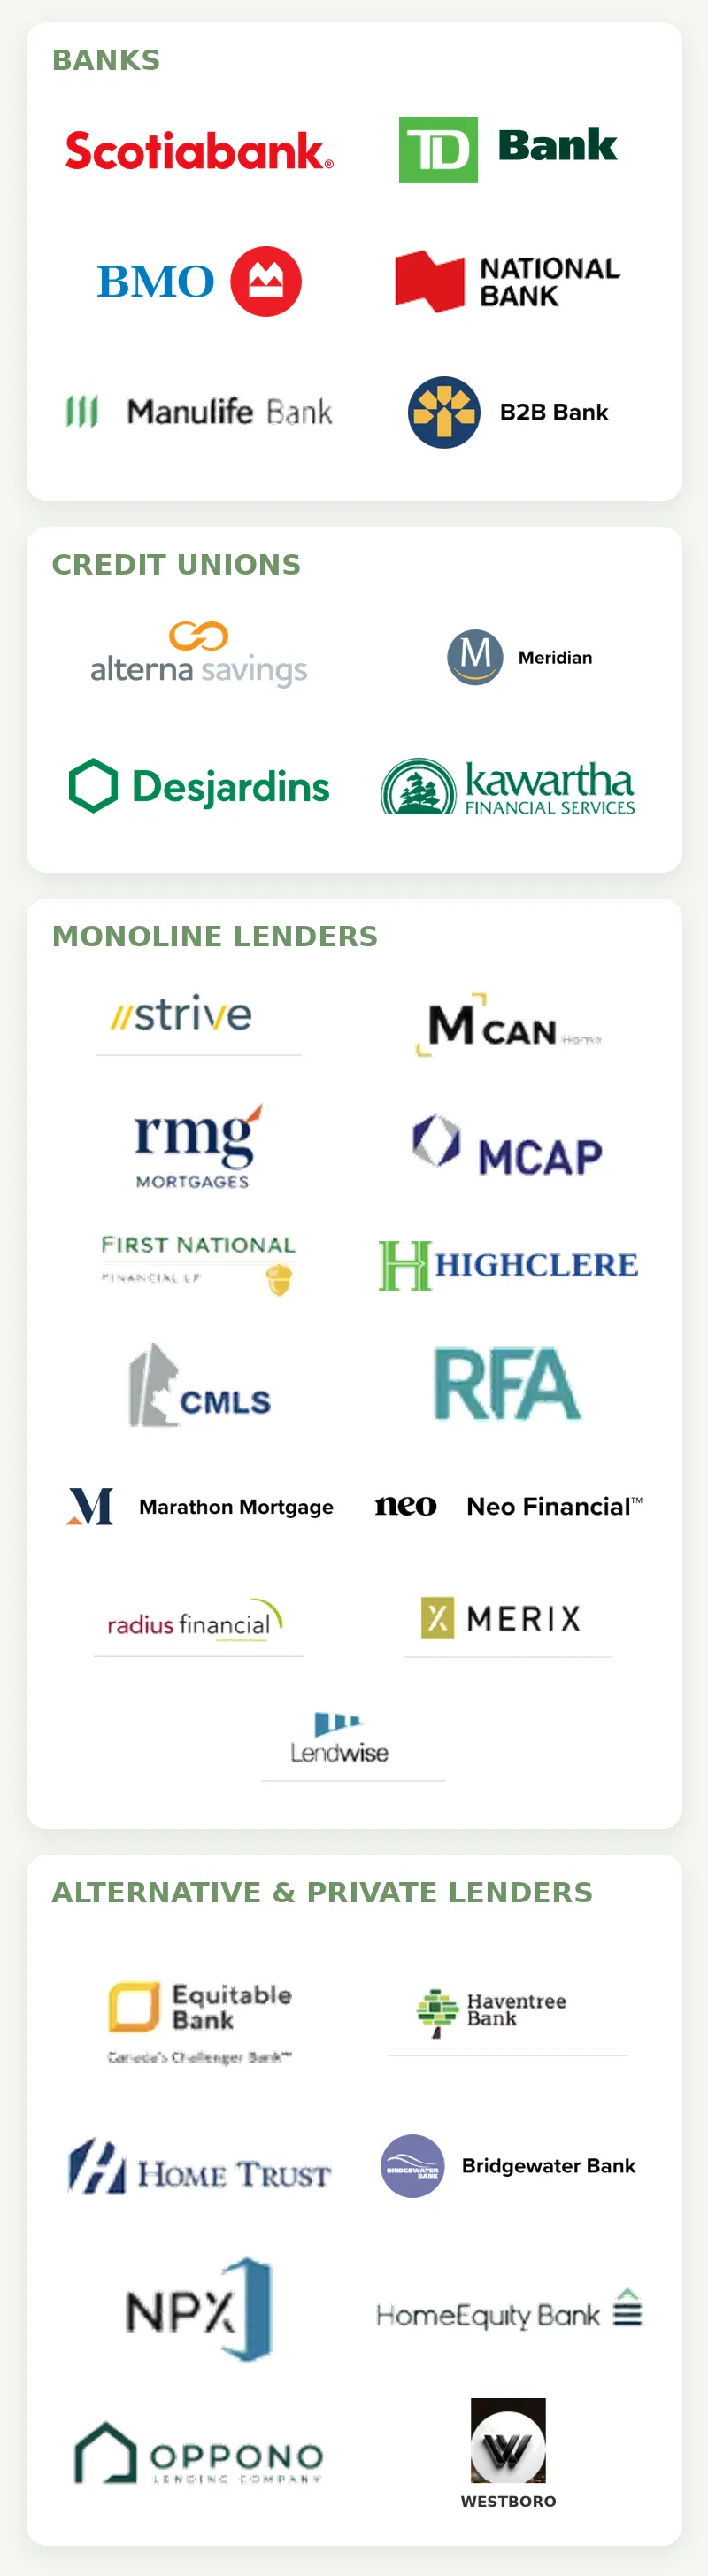
✓ Access to banks, credit unions, monoline and alternative lenders
✓ Personalized solutions for straightforward and complex needs
✓ Hands-on support from application through closing
PERSONAL MORTGAGE GUIDANCE
Prefer to speak with me directly?
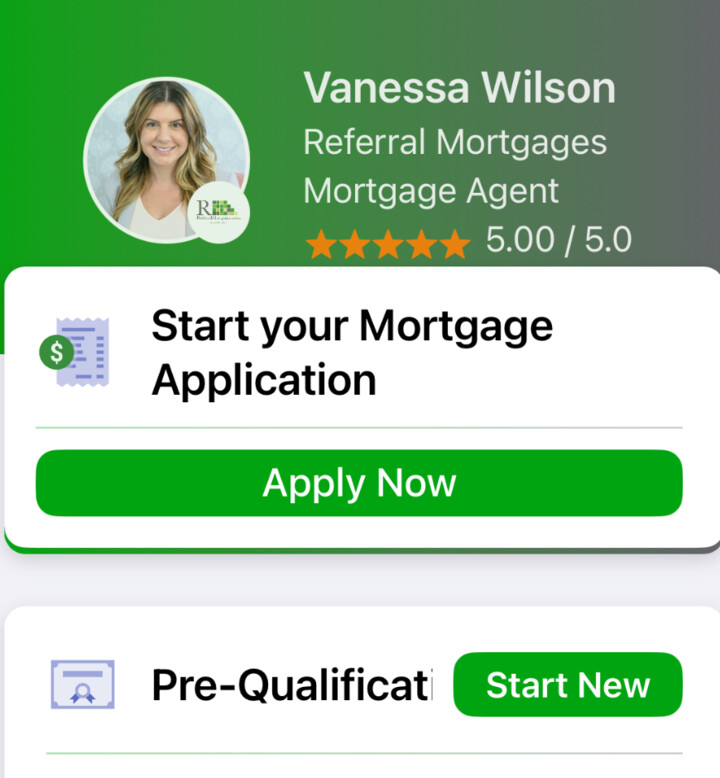
FREE CANADIAN MORTGAGE APP
See how much home you may be able to afford
Download my free Canadian Mortgage App, select 'Pre-Qualification' and tap 'Start New' to receive a quick estimate without affecting your credit score.
Pre-qualification provides an estimate only and is not a mortgage approval.
New Bank of Canada Rate Warning: Ottawa Mortgage Outlook
Could Canadian Interest Rates Rise Again? What Ottawa Homeowners Should Know
By Vanessa Wilson | Mortgage Agent Level 2
September 22, 2026
If you have a variable mortgage, an upcoming renewal or plans to buy a home in Ottawa, the latest comments from Bank of Canada Governor Tiff Macklem are a reason to review your mortgage strategy.
The message is that persistent inflation could require higher interest rates. However, these comments do not announce a rate increase or establish when one might happen.
For homeowners, the practical question is: how well would your mortgage and household budget handle a change in rates?
WHY IS THE BANK OF CANADA CONCERNED?
In his September 21 speech in Halifax, Macklem discussed an economy facing competing pressures. Higher energy prices linked to the conflict in the Middle East are pushing inflation above the Bank’s 2% target, while renewed trade tensions threaten economic growth.
The Bank must assess whether those price pressures will fade or become more widespread and lasting. Raising rates unnecessarily could weaken the economy. Waiting too long to address persistent inflation could make it harder to bring prices under control.
This leaves the outlook uncertain. Borrowers should leave room in their plans for more than one possible rate path.
WHAT DOES THIS MEAN FOR YOUR MORTGAGE?
If you have a variable-rate mortgage
Your mortgage rate is generally linked to your lender’s prime rate. If prime rises, your borrowing rate would typically rise too, according to your contract.
With adjustable payments, your payment changes when your mortgage rate changes. With fixed payments, a higher rate usually means more money goes toward interest and less toward principal. A fixed payment does not eliminate rate risk; your contract may require a payment adjustment if you reach a trigger point.
If you have a fixed-rate mortgage
Your contracted interest rate stays the same until the end of your term. A Bank of Canada announcement does not change that existing rate. Your next renewal is the point to plan for, because the rate available then could be different.
SHOULD YOU SWITCH FROM VARIABLE TO FIXED?
A headline alone is not enough to answer that question. I would want to review your current rate, the fixed rate being offered, your remaining term and how much payment uncertainty you can comfortably manage.
Before making a decision, let’s consider:
• How would different rate scenarios affect your monthly budget?
• How long do you expect to keep this property and mortgage?
• What conversion conditions, penalties or fees apply to your options?
• How much flexibility do you need to make extra payments, refinance or move?
The goal is to choose a mortgage that fits your finances and plans, even if interest rates do something unexpected.
RENEWING OR BUYING A HOME? START WITH YOUR NUMBERS
If your renewal is approaching, send me your current mortgage details and any renewal offer you receive. We can compare your options and discuss whether an available rate hold would suit your timing.
If you are buying, I recommend building your budget around a payment you can comfortably carry alongside property taxes, utilities, maintenance and other living expenses. We can also look at what a higher payment would mean before you commit to a purchase.
For existing homeowners, a useful next step is a mortgage check-in. Have your mortgage statement ready, along with any changes to your income, debts or plans. That gives us a much clearer starting point than a rate forecast alone.
LET’S REVIEW YOUR MORTGAGE STRATEGY
As an Ottawa mortgage broker, I help clients understand their options and make informed decisions about purchases, renewals and refinancing.
If you are wondering what these developments mean for you, let’s review your mortgage, compare the choices available and build a plan around your priorities.
Contact Vanessa Wilson at https://vwmortgages.ca to discuss your next steps.
MY LENDER NETWORK
More lenders. More options.
I compare solutions from banks, credit unions, monoline lenders and alternative lenders to find the right fit for you.
ABOUT VANESSA
Vanessa Wilson
Mortgage Agent Level 2
Licence #M21002877
Clear advice. Personalized mortgage strategies. Support you can count on.