Your Trusted Ottawa Mortgage Broker
Personalized mortgage solutions for homebuyers, homeowners, and real estate investors across Ottawa.
Mortgage Pre-Approval
Know your budget and shop for your new home with confidence
Mortgage Renewals
Compare your options before accepting your lender’s renewal offer
Mortgage Refinance
Access your home equity, consolidate debt, or improve your cash flow
Financing Solutions
Explore mortgage options tailored to your income and financial goals
Ready to Apply?
Complete my secure online application, and I’ll personally follow up with the next steps
MEET VANESSA WILSON
Mortgage advice built around your goals
Clear advice. Better options. Confident decisions.
Finding the right mortgage is about more than securing a competitive rate—it’s about choosing a strategy that supports your goals.
I’m Vanessa Wilson, an Ottawa Mortgage Agent Level 2. I help homebuyers and homeowners understand their options, compare lenders and move confidently through buying, renewing, refinancing or more complex financing.
✓ Access to banks, credit unions, monoline and alternative lenders
✓ Personalized solutions for straightforward and complex needs
✓ Hands-on support from application through closing
PERSONAL MORTGAGE GUIDANCE
Prefer to speak with me directly?
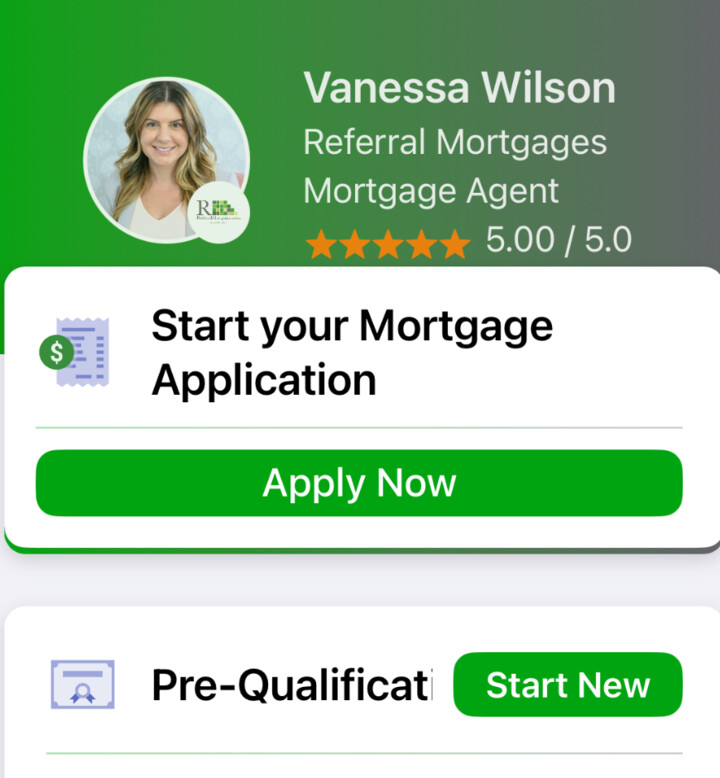
FREE CANADIAN MORTGAGE APP
See how much home you may be able to afford
Download my free Canadian Mortgage App, select 'Pre-Qualification' and tap 'Start New' to receive a quick estimate without affecting your credit score.
Pre-qualification provides an estimate only and is not a mortgage approval.
Variable-Rate Mortgage: Should You Lock Into a Fixed Rate?
Have a Variable-Rate Mortgage? What to Know About Possible Rate Increases
If you currently have a variable-rate mortgage, you may be wondering whether interest rates could rise—and whether you should consider locking into a fixed rate.
A rate increase is possible, but it is not certain. Canada’s economic data are sending mixed signals, making this a good time to understand your mortgage, review your budget and consider your options.
Why are rate increases being discussed?
Inflation reached 3.0% in August, while the Bank of Canada’s preferred measures of underlying inflation remained near 2%. This creates a mixed picture: overall prices are rising faster than the Bank’s target, but underlying inflation pressures appear more contained.
Higher energy costs and trade-related price pressures are among the concerns being monitored. If inflation becomes more persistent or spreads more broadly, the Bank may consider raising rates. However, that outcome will depend on how the economy develops.
Why might the Bank continue to hold rates?
A softer labour market is another consideration. Statistics Canada’s September employment report, released October 9, showed approximately 68,000 jobs lost. This followed a decline of approximately 42,000 jobs in August. These results suggest weakness in the labour market that the Bank will need to weigh alongside inflation.
For mortgage holders, the key takeaway is that no single economic report determines the next rate decision. Inflation, employment and economic growth all contribute to the outlook.
Important dates to watch
The Bank of Canada’s policy rate stood at 2.25% following its September 2 announcement. Upcoming dates include:
October 19, 2026: September inflation report.
October 28, 2026: Bank of Canada rate announcement.
December 9, 2026: Final scheduled Bank of Canada rate announcement of the year.
These are scheduled updates—not promises that rates will change.
What could a rate increase mean for your mortgage?
The impact depends on how your variable-rate mortgage is structured:
Adjustable payments: Your payment generally increases or decreases when your mortgage interest rate changes.
Fixed payments with a variable rate: Your payment may initially stay the same, but a higher interest rate means more goes toward interest and less toward principal. If rates rise sufficiently, your lender may require changes under your mortgage agreement.
Understanding which structure you have helps you prepare for changes to either your monthly budget or the pace at which you repay your mortgage.
Two steps to take if you are concerned
1. Ask your lender for its fixed-rate conversion options.
Request the available interest rate, term, payment and any conditions or costs associated with converting. Ask how the change would affect your remaining term, prepayment privileges and the cost of breaking your mortgage early.
Gathering this information gives you something concrete to review before making a decision.
2. Book a mortgage strategy review.
Whether your mortgage was arranged through me or elsewhere, we can review the options your lender provides and discuss how they fit your budget, comfort with payment changes and future plans.
We can also explore what potential rate increases could mean for your payments and whether building a larger cash buffer or adjusting your payment strategy makes sense.
There is no single right answer for every variable-rate borrower. The goal is to make an informed decision based on your mortgage and financial situation, without feeling pressured by headlines.
Schedule a call with Vanessa Wilson
Vanessa Wilson | Mortgage Agent Level 2 | Referral Mortgages
MY LENDER NETWORK
More lenders. More options.
I compare solutions from banks, credit unions, monoline lenders and alternative lenders to find the right fit for you.
ABOUT VANESSA
Vanessa Wilson
Mortgage Agent Level 2
Licence #M21002877
Clear advice. Personalized mortgage strategies. Support you can count on.