Your Trusted Ottawa Mortgage Broker
Personalized mortgage solutions for homebuyers, homeowners, and real estate investors across Ottawa.
Mortgage Pre-Approval
Know your budget and shop for your new home with confidence
Mortgage Renewals
Compare your options before accepting your lender’s renewal offer
Mortgage Refinance
Access your home equity, consolidate debt, or improve your cash flow
Financing Solutions
Explore mortgage options tailored to your income and financial goals
Ready to Apply?
Complete my secure online application, and I’ll personally follow up with the next steps
MEET VANESSA WILSON
Mortgage advice built around your goals
Clear advice. Better options. Confident decisions.
Finding the right mortgage is about more than securing a competitive rate—it’s about choosing a strategy that supports your goals.
I’m Vanessa Wilson, an Ottawa Mortgage Agent Level 2. I help homebuyers and homeowners understand their options, compare lenders and move confidently through buying, renewing, refinancing or more complex financing.
✓ Access to banks, credit unions, monoline and alternative lenders
✓ Personalized solutions for straightforward and complex needs
✓ Hands-on support from application through closing
PERSONAL MORTGAGE GUIDANCE
Prefer to speak with me directly?
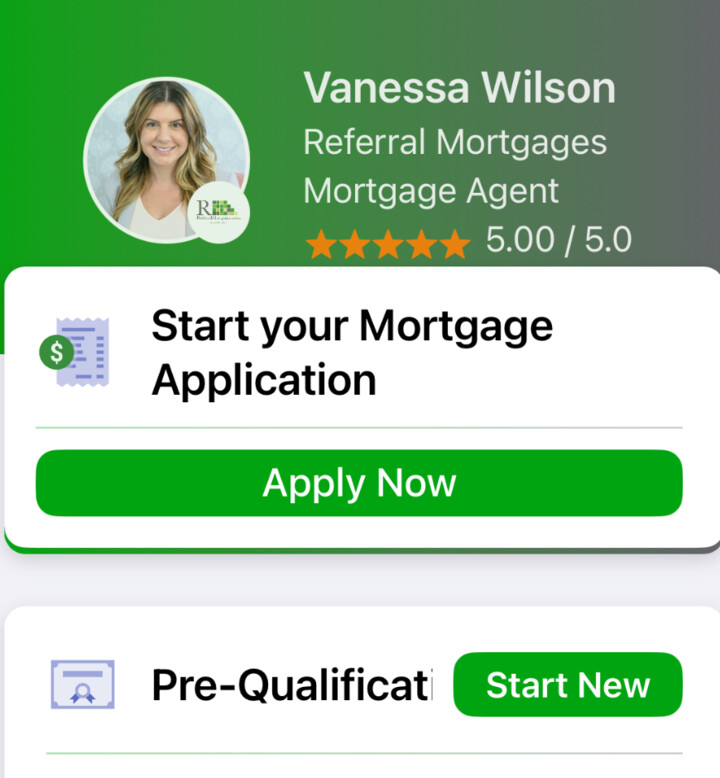
FREE CANADIAN MORTGAGE APP
See how much home you may be able to afford
Download my free Canadian Mortgage App, select 'Pre-Qualification' and tap 'Start New' to receive a quick estimate without affecting your credit score.
Pre-qualification provides an estimate only and is not a mortgage approval.
Trump tariff chaos: are BoC rate moves ahead?
U.S. Tariffs and Bank of Canada Rates: What Borrowers Need to Know
Canada is facing another round of trade uncertainty after new U.S. tariffs took effect on August 19. The latest measures impose a 50% tariff on a targeted group of Canadian products under Section 338 of the U.S. Tariff Act, as set out in the official U.S. proclamation.
For homeowners and homebuyers, the immediate question is understandable: could this economic pressure prompt the Bank of Canada to lower interest rates?
The short answer is that a rate cut is possible, but these tariffs alone are unlikely to trigger one. For now, the most likely outcome appears to be a continued hold.
What changed?
The new tariffs apply to U.S. imports representing approximately 5% of Canadian exports to the United States. They add to existing tariffs affecting products such as steel, aluminum, lumber and motor vehicles.
According to RBC Economics, the measures could mechanically increase the average effective U.S. tariff rate on Canadian exports from roughly 3% to approximately 6%.
The most affected industries include:
Plastic products
Electrical machinery
Furniture
Wood products
Quebec, British Columbia and Ontario are expected to experience the greatest regional exposure because of their concentration in these industries.
The impact will be significant for affected businesses and workers. However, the broader Canadian economy still has some protection. More than 80% of Canadian exports are expected to continue entering the United States duty-free under CUSMA, and the Canadian value-added content of the newly targeted goods represents approximately 0.4% of Canadian GDP and employment.
Will the Bank of Canada cut rates?
RBC Economics does not expect these tariffs, on their own, to cause the Bank of Canada to pivot to rate cuts. The economic pressure remains concentrated in a limited number of industries, which means targeted government support may be more appropriate than a broad interest-rate reduction.
The new tariffs may nevertheless reduce the likelihood of a rate increase in 2026. Trade uncertainty can weigh on business confidence, investment, exports and employment. At the same time, underlying inflation pressures—particularly when volatile energy prices are removed—have recently shown signs of moderation.
The Bank of Canada has maintained its overnight rate at 2.25% since October 2025. Its next interest-rate announcement is scheduled for September 2, 2026, according to the Bank of Canada’s official schedule.
For now, borrowers should prepare for rates to remain unchanged while recognizing that the outlook could shift if tariffs begin to cause broader weakness in employment, consumer spending or economic growth.
What does this mean for mortgage borrowers?
Variable-rate mortgages
Variable mortgage rates are linked to lender prime rates, which generally move with changes to the Bank of Canada’s overnight rate. If the Bank continues to hold, variable borrowing costs will likely remain stable. A future cut would provide relief, but borrowers should not build their budget around a reduction that has not yet occurred.
Fixed-rate mortgages
Fixed mortgage rates are influenced primarily by Government of Canada bond yields rather than directly by the Bank of Canada’s overnight rate. Trade uncertainty can create volatility in bond markets, so fixed rates may move before—or independently of—the Bank’s next decision.
Buying, renewing or refinancing
It may be tempting to delay a mortgage decision while waiting for lower rates. However, the direction and timing of future changes remain uncertain. The better strategy is to compare the options available today and select a mortgage that works within your current budget while offering the flexibility you may need later.
That can include reviewing:
Fixed versus variable rates
Term length
Prepayment privileges
Portability
Penalty calculations
The ability to convert a variable mortgage to a fixed rate
My perspective
The latest tariff escalation increases uncertainty, but it does not currently point to an immediate Bank of Canada rate cut. It does, however, make a rate increase this year appear less likely and strengthens the case for a prolonged hold.
Mortgage decisions should be based on affordability, risk tolerance and flexibility—not on trying to predict a single rate announcement. If you are purchasing a home, approaching a renewal or considering a refinance, I can review the available options and help you build a strategy that works under today’s rates while leaving room to benefit if conditions improve.
Contact Vanessa Wilson, Ottawa Mortgage Broker, for a personalized mortgage review.
This article is for general information only and does not constitute financial advice. Mortgage products, rates and qualification requirements are subject to change. Information is current as of August 24, 2026.
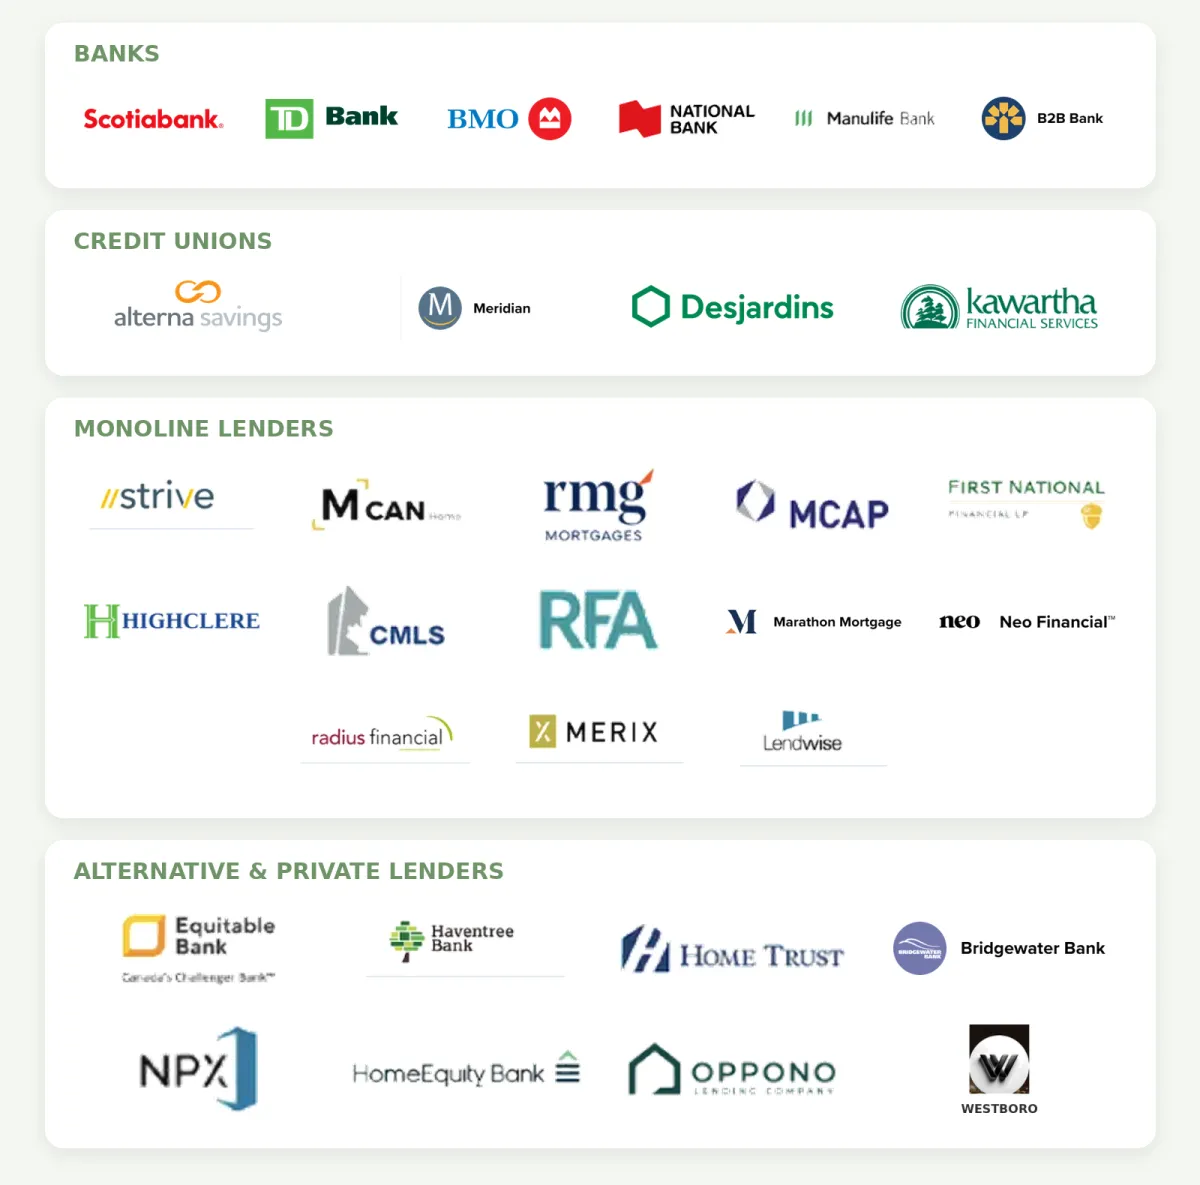
MY LENDER NETWORK
More lenders. More options.
I compare solutions from banks, credit unions, monoline lenders and alternative lenders to find the right fit for you.
ABOUT VANESSA
Vanessa Wilson
Mortgage Agent Level 2
Licence #M21002877
Clear advice. Personalized mortgage strategies. Support you can count on.