Your Trusted Ottawa Mortgage Broker
Personalized mortgage solutions for homebuyers, homeowners, and real estate investors across Ottawa.
Mortgage Pre-Approval
Know your budget and shop for your new home with confidence
Mortgage Renewals
Compare your options before accepting your lender’s renewal offer
Mortgage Refinance
Access your home equity, consolidate debt, or improve your cash flow
Financing Solutions
Explore mortgage options tailored to your income and financial goals
Ready to Apply?
Complete my secure online application, and I’ll personally follow up with the next steps
MEET VANESSA WILSON
Mortgage advice built around your goals
Clear advice. Better options. Confident decisions.
Finding the right mortgage is about more than securing a competitive rate—it’s about choosing a strategy that supports your goals.
I’m Vanessa Wilson, an Ottawa Mortgage Agent Level 2. I help homebuyers and homeowners understand their options, compare lenders and move confidently through buying, renewing, refinancing or more complex financing.
✓ Access to banks, credit unions, monoline and alternative lenders
✓ Personalized solutions for straightforward and complex needs
✓ Hands-on support from application through closing
PERSONAL MORTGAGE GUIDANCE
Prefer to speak with me directly?
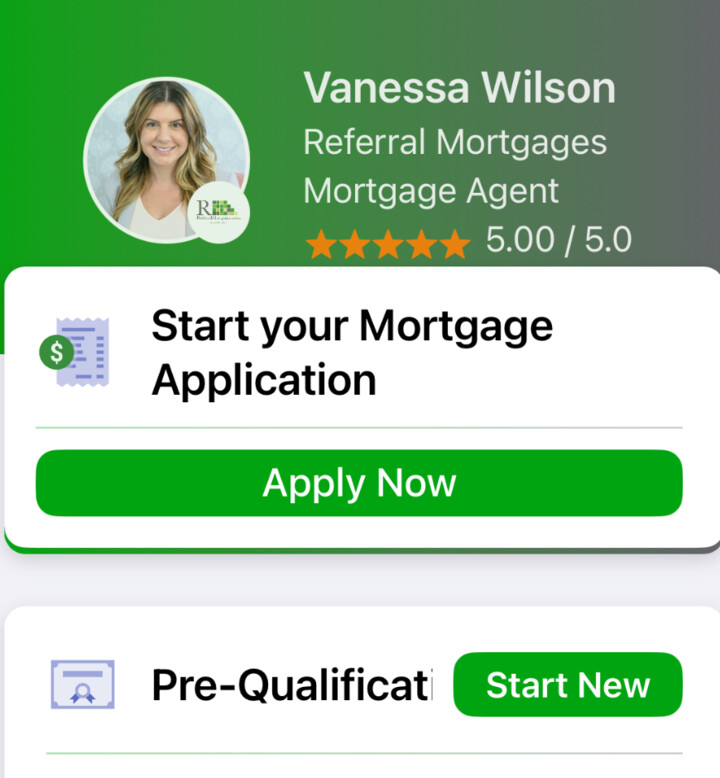
FREE CANADIAN MORTGAGE APP
See how much home you may be able to afford
Download my free Canadian Mortgage App, select 'Pre-Qualification' and tap 'Start New' to receive a quick estimate without affecting your credit score.
Pre-qualification provides an estimate only and is not a mortgage approval.
Canada’s 5-Year Bond Yield Hits a 52-Week High: What It Means for Mortgage Rates
Canada’s 5-year government bond yield has reached a new 52-week high, adding further pressure to fixed mortgage rates.
The yield closed Tuesday at 3.484%, an increase of 3.6 basis points for the day. It has risen by approximately 15 basis points over the past month and roughly 73 basis points compared with one year ago.
Why does this matter to Canadian homeowners and homebuyers? The 5-year Government of Canada bond yield is one of the main benchmarks lenders use when pricing fixed mortgage rates.
What Is Driving Bond Yields Higher?
The increase in Canadian bond yields occurred alongside renewed pressure in the United States bond market.
The U.S. 10-year Treasury yield briefly reached 4.85%, its highest level since November 2023. The increase followed details of a planned US$6-billion Treasury bond buyback that disappointed some investors. Yields later eased after a strong auction of 10-year Treasury bonds.
Oil prices are also contributing to inflation concerns.
Brent crude oil closed above US$100 per barrel, settling at US$101.21 as tensions in the Middle East continued to escalate. Higher energy prices can increase transportation, manufacturing and household costs, potentially making it more difficult for inflation to remain under control.
If inflationary pressure persists, interest rates may need to remain elevated for longer than borrowers and financial markets had previously expected.
How Bond Yields Affect Fixed Mortgage Rates
Fixed mortgage rates are influenced primarily by Government of Canada bond yields with comparable terms.
When bond yields rise, lenders generally face higher funding costs. If yields remain elevated, lenders may respond by:
• Increasing fixed mortgage rates
• Withdrawing lower-rate promotions
• Reducing available rate discounts
• Repricing mortgage products with little notice
Mortgage rates do not always move immediately or by exactly the same amount as bond yields. Each lender has its own funding costs, pricing strategy and risk considerations. However, a sustained increase in the 5-year yield generally creates upward pressure on fixed rates.
What About Variable Mortgage Rates?
Variable mortgage rates are not directly priced from the 5-year bond yield.
Instead, variable rates are based on a lender’s prime rate, which is influenced by the Bank of Canada’s overnight rate. Bond-market movements can still provide important information about inflation expectations and where financial markets believe interest rates may be headed.
Fixed and variable rates therefore react to different factors, which is why choosing between them should involve more than simply comparing today’s rates.
What This Means for Homebuyers
If you are planning to purchase a home, rising bond yields could affect the fixed rates available when you are ready to submit an offer.
Obtaining a mortgage pre-approval and rate hold may help protect you if fixed rates increase during your home search. A pre-approval can also help you understand:
• Your estimated maximum purchase price
• The down payment and closing costs you will need
• Your estimated mortgage payment
• Whether a fixed or variable mortgage may suit your plans
• The documents and conditions required for approval
A rate hold does not guarantee final mortgage approval. The lender must still approve the borrower, property, income, credit and down-payment documentation once there is an accepted offer.
What This Means for Homeowners With an Upcoming Renewal
Homeowners approaching their mortgage renewal should begin reviewing their options before receiving or accepting their lender’s renewal offer.
Starting early provides time to:
• Compare rates and mortgage terms from multiple lenders
• Review fixed and variable options
• Consider prepayment privileges and potential penalties
• Determine whether refinancing could improve cash flow
• Consolidate higher-interest debt when appropriate
• Secure a rate before the current mortgage reaches maturity
The lowest rate is not always the best mortgage. Restrictions involving prepayments, portability, early renewal and penalties can have a significant financial impact over the life of the mortgage.
Should You Lock In a Fixed Rate Now?
There is no single answer that works for every borrower.
A fixed mortgage may provide greater payment stability and protection if rates remain elevated or increase further. A variable mortgage may offer more flexibility and a lower penalty if the mortgage needs to be broken early, but it also exposes the borrower to possible rate and payment changes.
The right choice depends on your budget, future plans, risk tolerance and how long you expect to keep the mortgage or property.
Let’s Review Your Mortgage Strategy
Bond yields and lender pricing can change quickly. If you are purchasing a home, renewing your mortgage or considering a refinance, reviewing your options early can help you make an informed decision before rates change.
As an Ottawa mortgage broker, I compare mortgage solutions from banks, credit unions, mortgage finance companies and alternative lenders. I can help you understand how the latest market changes may affect your mortgage and determine which option best supports your short- and long-term plans.
Contact Vanessa Wilson Mortgages to discuss your mortgage options by clicking here
The information provided is general in nature and is not financial or legal advice. Mortgage rates, qualifications and product availability are subject to change and lender approval.
MY LENDER NETWORK
More lenders. More options.
I compare solutions from banks, credit unions, monoline lenders and alternative lenders to find the right fit for you.
ABOUT VANESSA
Vanessa Wilson
Mortgage Agent Level 2
Licence #M21002877
Clear advice. Personalized mortgage strategies. Support you can count on.