Your Trusted Ottawa Mortgage Broker
Personalized mortgage solutions for homebuyers, homeowners, and real estate investors across Ottawa.
Mortgage Pre-Approval
Know your budget and shop for your new home with confidence
Mortgage Renewals
Compare your options before accepting your lender’s renewal offer
Mortgage Refinance
Access your home equity, consolidate debt, or improve your cash flow
Financing Solutions
Explore mortgage options tailored to your income and financial goals
Ready to Apply?
Complete my secure online application, and I’ll personally follow up with the next steps
MEET VANESSA WILSON
Mortgage advice built around your goals
Clear advice. Better options. Confident decisions.
Finding the right mortgage is about more than securing a competitive rate—it’s about choosing a strategy that supports your goals.
I’m Vanessa Wilson, an Ottawa Mortgage Agent Level 2. I help homebuyers and homeowners understand their options, compare lenders and move confidently through buying, renewing, refinancing or more complex financing.
✓ Access to banks, credit unions, monoline and alternative lenders
✓ Personalized solutions for straightforward and complex needs
✓ Hands-on support from application through closing
PERSONAL MORTGAGE GUIDANCE
Prefer to speak with me directly?
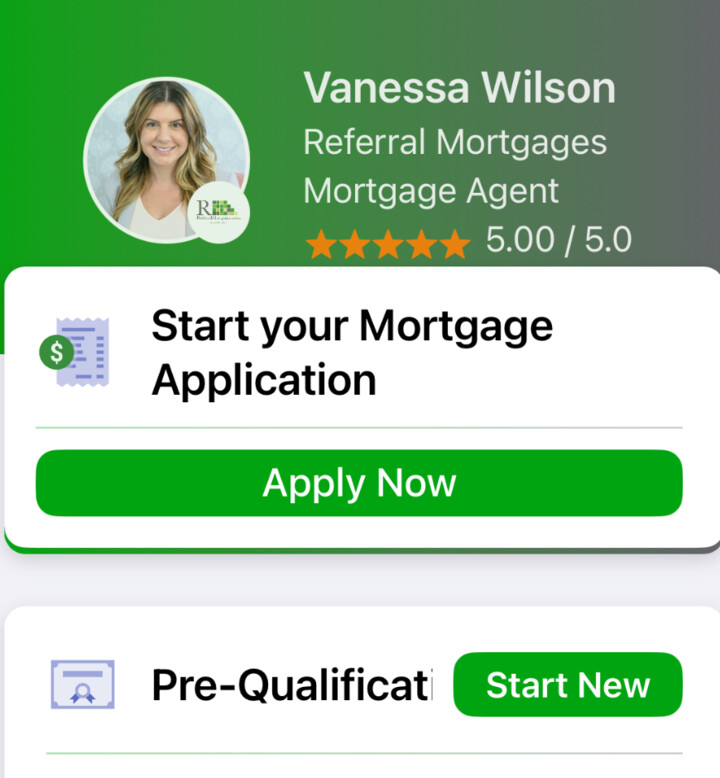
FREE CANADIAN MORTGAGE APP
See how much home you may be able to afford
Download my free Canadian Mortgage App, select 'Pre-Qualification' and tap 'Start New' to receive a quick estimate without affecting your credit score.
Pre-qualification provides an estimate only and is not a mortgage approval.
Bank of Canada Holds Rate at 2.25% | Mortgage Update
BANK OF CANADA HOLDS ITS POLICY RATE AT 2.25%:
WHAT THIS MEANS FOR MORTGAGE BORROWERS
Published September 2, 2026
The Bank of Canada announced today that it is maintaining its policy interest rate at 2.25%. This marks the seventh consecutive rate decision without a change.
For mortgage borrowers, the immediate takeaway is straightforward: there is no change today for most variable-rate mortgages or home equity lines of credit tied to lender prime rates. However, this does not necessarily mean that all mortgage rates will remain unchanged.
WHY DID THE BANK OF CANADA HOLD ITS RATE?
The Bank of Canada is currently trying to balance two competing risks.
On one side, renewed trade tensions between Canada and the United States could weaken consumer confidence, slow business investment and place pressure on economic growth.
On the other, the reintroduction of aggressive U.S. tariffs on Canadian exports, higher import costs and elevated energy prices could contribute to inflation.
The Governing Council noted that Canada’s economy experienced a broad recovery during the second quarter of 2026, demonstrating resilience despite difficult global conditions.
However, the ongoing war in the Middle East has placed upward pressure on energy prices and longer-term bond yields. Renewed tariffs have also created another potential source of inflation.
So far, underlying inflation has remained around the Bank of Canada’s target despite the energy-price shock that began in March. The concern is whether higher energy costs and tariffs will eventually spread more broadly through consumer prices.
With inflation requiring continued attention and the economic effects of the trade conflict difficult to predict, the Bank has chosen to remain on the sidelines for now.
In practical terms, the Bank appears to be waiting for clearer evidence before deciding whether its next move should be a rate decrease or an increase.
WHERE COULD INTEREST RATES GO NEXT?
The Bank of Canada did not provide a clear signal about the timing or direction of its next move.
The outlook remains unusually uncertain. Future decisions will depend on how inflation, economic growth, energy prices and trade conditions develop.
Trading Economics currently forecasts the Canadian policy rate at approximately 2.25% at the end of this quarter and through 2027, before trending toward approximately 2.00% in 2028.
It is important to understand that these figures are based on Trading Economics’ global macroeconomic models and analyst expectations. They are not Bank of Canada guidance or guaranteed outcomes.
Interest-rate forecasts can change quickly when inflation, employment, geopolitical events or trade policies develop differently than expected. Borrowers should therefore avoid selecting a mortgage solely because of one interest-rate forecast.
WHAT DOES THIS MEAN FOR VARIABLE-RATE MORTGAGES?
Variable mortgage rates are generally based on a lender’s prime rate.
Because the Bank of Canada did not change its policy rate, lenders are not expected to change their prime rates as a direct result of today’s announcement.
If you have an adjustable-rate mortgage, your payment should remain unchanged because of this decision.
If you have a variable-rate mortgage with a fixed payment, your payment and the amount applied toward the mortgage principal should also remain unchanged for now.
Borrowers should still review the specific terms of their mortgage. Variable-rate products can differ significantly between lenders, including how payments adjust, how trigger-rate provisions work and what happens when interest rates change.
WHAT ABOUT FIXED MORTGAGE RATES?
Fixed mortgage rates do not move directly with the Bank of Canada’s policy rate.
They are influenced more heavily by Government of Canada bond yields, lender funding costs, financial-market expectations and competition between lenders.
This means fixed mortgage rates can rise or fall even when the Bank of Canada holds its policy rate steady.
Trade uncertainty, inflation data and expectations about future Bank of Canada decisions can all affect bond markets and, in turn, fixed mortgage pricing.
If you are purchasing a home, renewing your mortgage or refinancing, it is important to compare more than the advertised interest rate.
A mortgage’s penalty calculation, prepayment privileges, portability, term and overall flexibility can have a much larger financial impact over time.
SHOULD YOU CHOOSE A FIXED OR VARIABLE MORTGAGE?
There is no single answer that is right for every borrower.
A fixed-rate mortgage may be more suitable if predictable payments and protection from future rate increases are your priorities.
A variable-rate mortgage may appeal to someone who is comfortable with possible changes to their payment or interest costs and values flexibility. Penalties on variable-rate mortgages are also commonly limited to three months’ interest.
The right choice depends on your budget, future plans, risk tolerance and the specific mortgage products available to you—not simply on a prediction about where interest rates may go next.
IF YOUR MORTGAGE IS COMING UP FOR RENEWAL
Do not assume that your current lender’s renewal offer is automatically your best option.
I recommend beginning your mortgage review approximately four to six months before your maturity date.
This gives you time to compare lenders, determine whether your existing mortgage structure still fits your plans and prepare the necessary documents if moving to another lender makes sense.
Even when the Bank of Canada holds its policy rate, lenders continue to adjust their mortgage pricing and promotions.
Starting early allows you to make a well-informed decision based on the broader market instead of feeling pressured to accept a deadline-driven renewal offer.
WHAT SHOULD OTTAWA HOMEBUYERS AND HOMEOWNERS DO NOW?
Today’s announcement is an important reminder that mortgage planning should not be based on one Bank of Canada decision alone.
If you are purchasing a home, obtain a fully reviewed pre-approval and understand how changes in interest rates, property taxes and condominium fees could affect your purchasing power.
If you already own a home, this may be a good time to review your renewal date, current interest rate, prepayment privileges and any higher-interest debts.
The goal is not to predict every Bank of Canada decision. It is to choose a mortgage strategy that remains affordable and manageable under more than one possible interest-rate scenario.
LET’S REVIEW YOUR MORTGAGE OPTIONS
Whether you are purchasing, renewing or refinancing, I can compare options from multiple lenders and explain how the current interest-rate environment applies to your specific situation.
Book a mortgage consultation with Vanessa Wilson:
https://api.leadconnectorhq.com/widget/bookings/vwmortgages
This article is intended for general information only and does not constitute financial advice. Mortgage rates, products and qualification requirements are subject to change and borrower approval.
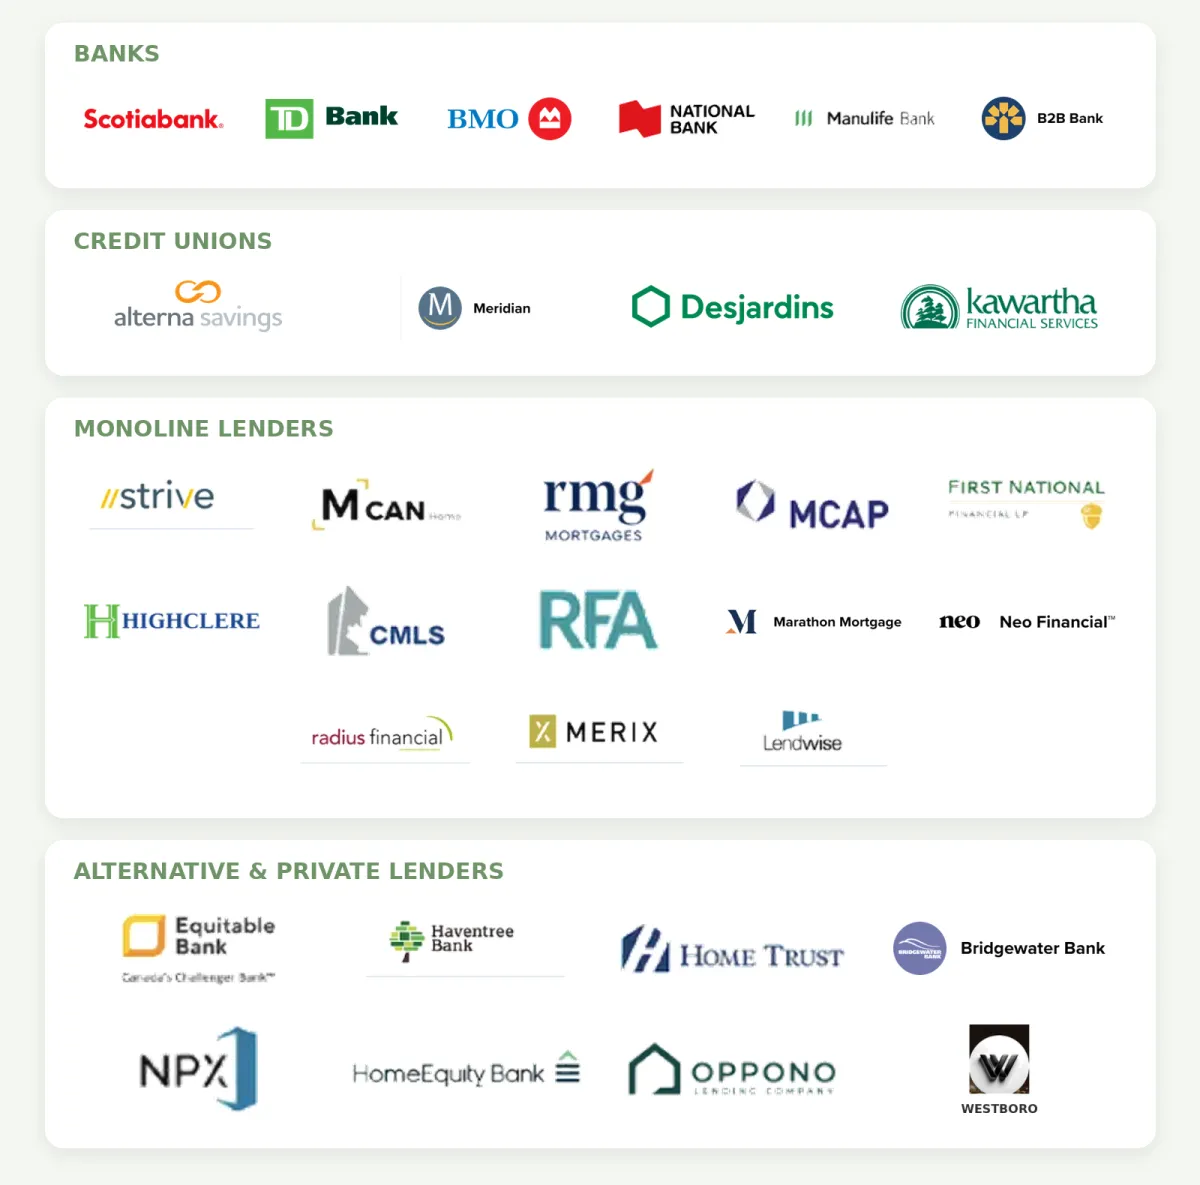
MY LENDER NETWORK
More lenders. More options.
I compare solutions from banks, credit unions, monoline lenders and alternative lenders to find the right fit for you.
ABOUT VANESSA
Vanessa Wilson
Mortgage Agent Level 2
Licence #M21002877
Clear advice. Personalized mortgage strategies. Support you can count on.