Your Trusted Ottawa Mortgage Broker
Personalized mortgage solutions for homebuyers, homeowners, and real estate investors across Ottawa.
Mortgage Pre-Approval
Know your budget and shop for your new home with confidence
Mortgage Renewals
Compare your options before accepting your lender’s renewal offer
Mortgage Refinance
Access your home equity, consolidate debt, or improve your cash flow
Financing Solutions
Explore mortgage options tailored to your income and financial goals
Ready to Apply?
Complete my secure online application, and I’ll personally follow up with the next steps
MEET VANESSA WILSON
Mortgage advice built around your goals
Clear advice. Better options. Confident decisions.
Finding the right mortgage is about more than securing a competitive rate—it’s about choosing a strategy that supports your goals.
I’m Vanessa Wilson, an Ottawa Mortgage Agent Level 2. I help homebuyers and homeowners understand their options, compare lenders and move confidently through buying, renewing, refinancing or more complex financing.
✓ Access to banks, credit unions, monoline and alternative lenders
✓ Personalized solutions for straightforward and complex needs
✓ Hands-on support from application through closing
PERSONAL MORTGAGE GUIDANCE
Prefer to speak with me directly?
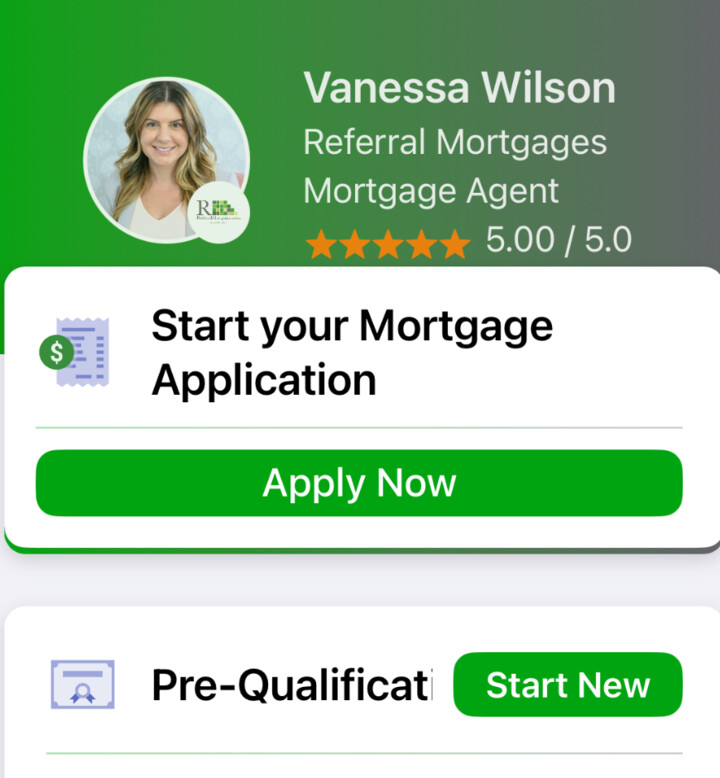
FREE CANADIAN MORTGAGE APP
See how much home you may be able to afford
Download my free Canadian Mortgage App, select 'Pre-Qualification' and tap 'Start New' to receive a quick estimate without affecting your credit score.
Pre-qualification provides an estimate only and is not a mortgage approval.
Bank of Canada Rate Forecast 2026–2027: Fixed vs Variable Mortgages
With the Bank of Canada's next interest rate announcement scheduled for October 28, 2026, I wanted to share some important new information that may help you evaluate your variable-rate mortgage.
The Bank of Canada's policy rate currently sits at 2.25% (the prime rate is at 4.45% and your variable rate mortgage typically has a discount on that), but new forecasts from Canada's six major banks reveal significantly different expectations for where interest rates are headed.
What Are Canada's Major Banks Predicting?
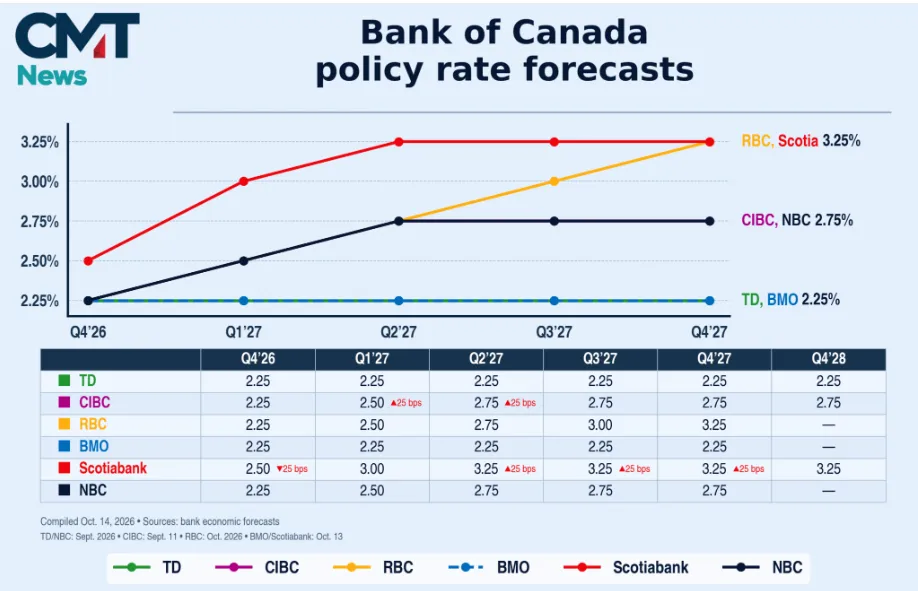
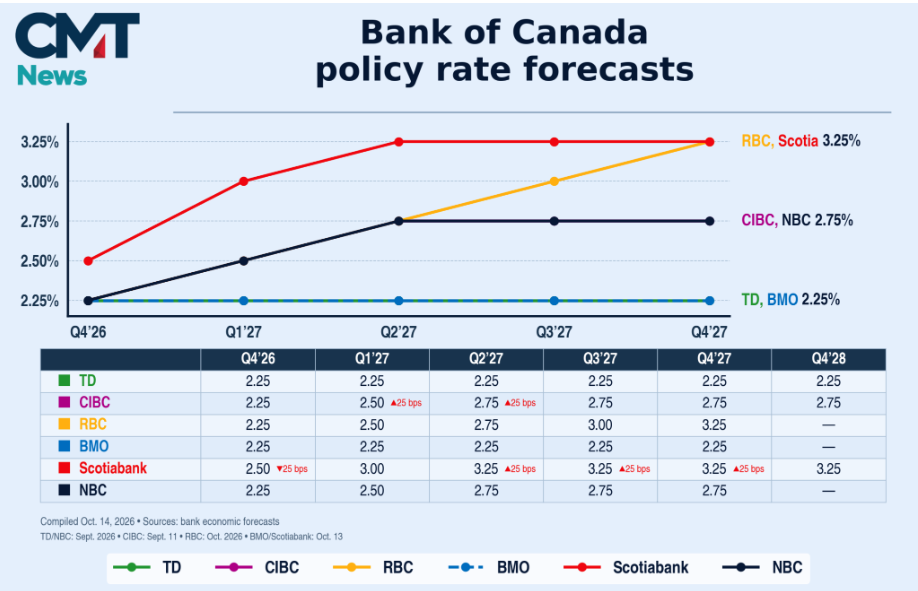
According to forecasts compiled by Canadian Mortgage Trends on October 14, 2026:
TD: Expects the Bank of Canada to maintain its current 2.25% policy rate through 2028.
BMO: Forecasts no rate changes through 2027, although it acknowledges that the risk of increases is growing.
CIBC and National Bank: Expect the policy rate to reach 2.75% by the end of 2027.
RBC: Forecasts gradual increases, reaching 3.25% by the end of 2027.
Scotiabank: Has the most aggressive outlook, forecasting an increase to 2.50% by the end of 2026 and 3.25% by the second quarter of 2027.
Why Is This Important?
These forecasts demonstrate that even Canada's largest financial institutions cannot agree on the direction or timing of future interest rate changes.
Two major banks expect rates to remain unchanged, while four anticipate increases of varying degrees.
These are economic forecasts, not guarantees. They will continue to evolve as new inflation, employment and economic data become available.
What Has Changed Recently?
Recent economic developments have added further uncertainty:
Canada's labour market continues to show signs of weakness, which could reduce inflationary pressures.
Higher energy prices and tariff-related costs remain potential sources of inflation.
Financial markets have begun pricing in the possibility of rate increases in 2027, despite the weaker economic outlook.
The Bank of Canada must balance these competing factors when determining its next move.
Should You Stay Variable or Consider Locking Into a Fixed Rate?
This is an important question, particularly for homeowners who currently have an attractive variable or adjustable-rate mortgage.
In some cases, the difference between a client's existing variable rate and an available fixed rate can be one percentage point or more.
For example, consider a $400,000 mortgage with a remaining 25-year amortization:
At a 3.50% variable rate, the approximate monthly payment is $1,997.
At a 4.50% fixed rate, the approximate monthly payment is $2,214.
That's approximately $217 more per month, or $2,604 annually, to lock into the higher fixed rate.
These are illustrative payments using Canadian semi-annual compounding. Actual payments and savings depend on your mortgage terms, remaining amortization and future rate changes.
While locking into a fixed rate provides payment certainty, it may also mean immediately increasing your borrowing costs.
For some homeowners, that certainty is worth the additional expense. For others, maintaining a lower variable rate and retaining flexibility may be more beneficial.
Another Strategy Worth Considering
If you are comfortable with your variable rate, you may wish to consider voluntarily increasing your mortgage payments rather than locking into a higher fixed rate.
This strategy can allow you to:
Pay down your mortgage principal faster while rates remain lower.
Build additional room in your household budget for potential future rate increases.
Reduce your outstanding mortgage balance and future interest costs.
Maintain the benefits and flexibility of your existing variable-rate mortgage.
Whether this strategy makes sense depends on your mortgage product, prepayment privileges, cash flow and financial objectives.
A Word of Caution If Your Lender Contacts You
If your lender contacts you offering to convert your variable mortgage into a fixed rate, please speak with me before accepting the offer.
Your lender has a commercial interest in retaining your mortgage, and the offer should be reviewed carefully.
We should consider not only the interest rate being offered, but also the mortgage term, potential prepayment penalties, flexibility and how the proposed change fits your longer-term plans.
Remember, once you convert to a fixed-rate mortgage, returning to a variable rate before maturity may involve substantial penalties.
My Commitment to You
My role is to provide you with independent information, explain the potential benefits and risks of each option, and help you make an informed decision that reflects your financial goals and comfort with uncertainty.
There is no single mortgage strategy that is right for everyone.
Would You Like to Review Your Mortgage Options?
If you would like to review your current rate, compare fixed and variable options, or discuss how potential Bank of Canada increases could affect your payments, I would be happy to go through the numbers with you.
CLICK HERE TO SCHEDULE A MORTGAGE REVIEW
Even if you decide to make no changes, understanding your options can provide valuable peace of mind.
I will continue monitoring economic developments and keeping you informed as new information becomes available.
My Best,
Vanessa Wilson
Mortgage Agent Level 2
Referral Mortgages
Ottawa Mortgage Broker
www.vwmortgages.ca
Source: Canadian Mortgage Trends, October 14, 2026. Bank forecasts are subject to change. Mortgage examples are illustrative and do not represent a rate offer or guarantee.
MY LENDER NETWORK
More lenders. More options.
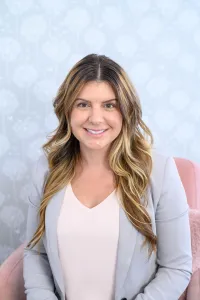
I compare solutions from banks, credit unions, monoline lenders and alternative lenders to find the right fit for you.
ABOUT VANESSA
Vanessa Wilson
Mortgage Agent Level 2
Licence #M21002877
Clear advice. Personalized mortgage strategies. Support you can count on.